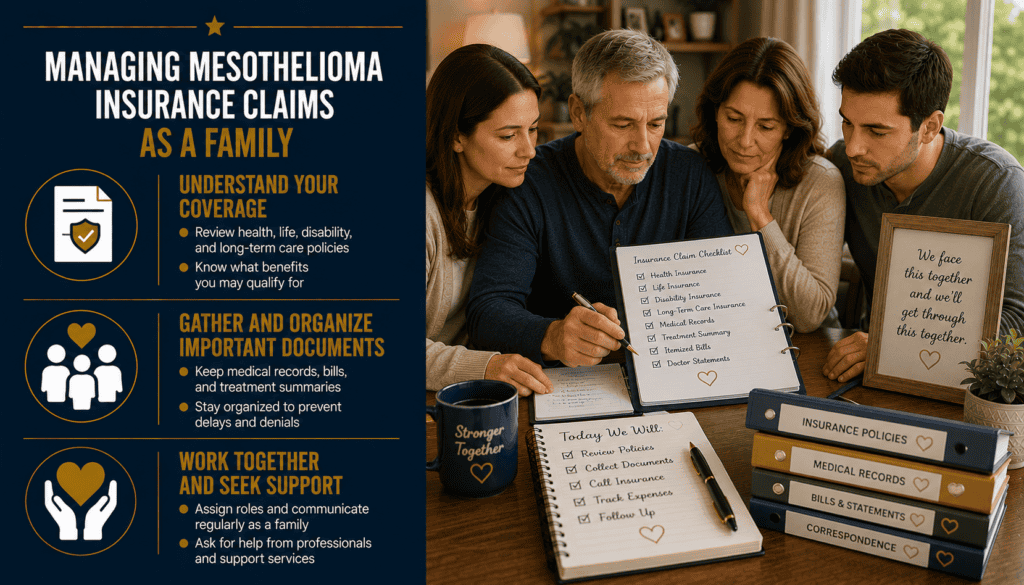
Managing Insurance Claims as a Family After a Mesothelioma Diagnosis
A mesothelioma diagnosis can quickly generate insurance paperwork from hospitals, specialists, imaging centers, laboratories, pharmacies and other providers. Families may also be dealing with Medicare, employer coverage, supplemental insurance, prescription plans and a possible asbestos compensation claim at the same time. Keeping these systems organized can reduce missed deadlines, duplicate payments and confusion about who is responsible for a bill.
The most useful approach is to treat insurance administration as a recordkeeping project. Identify every plan, appoint an authorized family representative when needed, keep each Explanation of Benefits (EOB), match bills to insurance decisions, document calls and preserve denial and appeal notices. Health-insurance claims and asbestos legal claims can interact, but they are not the same process.
🗂️ Start With One Family Insurance File
Create one central paper or digital file for insurance information. Divide it by insurer or plan and keep a chronological log of important contacts. Record the date, organization, representative’s name, phone number, reference number, question asked and response received.
Keep original notices whenever possible. Scan important documents for backup, but do not discard originals simply because a digital copy exists.
For the broader family-claims resource, visit Family Member Mesothelioma Claims.
🏥 Identify Every Source of Health Coverage
Make a list of every plan that may pay medical expenses. This can include Original Medicare, Medicare Advantage, Medicare Part D, employer or retiree health insurance, a spouse’s employer plan, supplemental coverage, Medicaid, VA-related coverage when applicable, workers’ compensation or other insurance.
Record the member number, group number, effective dates, plan phone number and whether the plan is primary or secondary. Do not assume the card used at the doctor’s office is necessarily the payer that must pay first.
👤 Choose an Authorized Family Representative
A family member helping with insurance may need formal authorization before an insurer will discuss protected health or claims information. Medicare, for example, allows a beneficiary to appoint a representative to help with claims and appeals and uses authorization procedures for disclosure of personal health information.
Private plans may use their own authorized-representative forms. Complete the required paperwork early rather than waiting until an urgent denial occurs.
📄 Track Every Claim and Explanation of Benefits
An Explanation of Benefits is not necessarily a bill. It generally explains what the provider charged, what the plan allowed, what the insurer paid and what amount may be assigned to the patient.
| Track | Why it matters |
|---|---|
| Date of service | Connects the claim to the correct treatment |
| Provider | Identifies who submitted the claim |
| Claim number | Helps with insurer follow-up |
| Amount billed | Shows provider charge |
| Allowed amount | Shows plan’s recognized amount |
| Insurance payment | Shows what the plan paid |
| Patient responsibility | Shows the amount assigned to the patient |
| Status/denial code | Identifies whether follow-up is needed |
💳 Match Medical Bills to Insurance Decisions
Before paying a large medical bill, compare it with the corresponding EOB or Medicare notice. Check the patient name, provider, date of service, procedure and amount assigned to the patient.
If the insurer shows that a claim is still pending, needs corrected coding or should be resubmitted, contact the provider’s billing office before assuming the entire balance is due. Keep notes of the conversation.
🚫 Understand Why a Claim Was Denied
A denial can result from many issues: lack of prior authorization, an out-of-network provider, coding or billing errors, missing information, a plan exclusion, medical-necessity review, coordination-of-benefits questions or an eligibility issue.
Read the written denial rather than relying only on a phone explanation. The notice should identify the reason and explain available appeal rights.
📝 Appeal Coverage or Payment Denials
For many employer-sponsored plans governed by ERISA, the U.S. Department of Labor explains that a claimant generally has at least 180 days to request review of a denied health-benefit claim, although the plan documents should be checked for the exact procedure. The plan must provide relevant claim documents on request under applicable rules.
Build the appeal around the stated denial reason. Include supporting medical records, physician information, authorization records, plan language and other evidence that directly addresses the issue. Keep a complete copy of everything submitted and proof of delivery.
⏰ Track Insurance Appeal Deadlines
Insurance deadlines can be separate from legal filing deadlines for an asbestos lawsuit or trust claim. Put the deadline from every denial notice into a shared family calendar and identify who is responsible for responding.
Do not assume that calling the insurer or asking a provider to correct a claim automatically extends an appeal deadline. Confirm extensions or revised deadlines in writing when possible.
🏛️ Medicare Claims and Appeals
Medicare beneficiaries can appeal coverage or payment decisions. Medicare explains that appeals may be available when Medicare or a Medicare plan refuses to cover or pay for a service, supply, item or drug, changes what the beneficiary must pay, or stops coverage for services believed to still be needed.
A trusted family member can be appointed as a representative. Families should follow the instructions and deadlines on the Medicare Summary Notice or plan denial rather than relying on a general deadline from another insurance system.
🔄 Coordination of Benefits
When a person has more than one source of coverage, coordination-of-benefits rules determine which payer is primary and which may pay second. CMS explains that Medicare’s coordination process identifies other available health coverage and determines payment responsibility.
Families should promptly report changes in employer coverage, retirement status or other insurance when required. Incorrect coordination information can cause claims to be denied or paid in the wrong order.
⚖️ Liability Claims and Medicare Secondary Payer Rules
A mesothelioma compensation claim can create a separate Medicare issue. Under Medicare Secondary Payer rules, Medicare generally does not pay for medical items or services when payment has been made or can reasonably be expected from liability insurance, no-fault insurance or workers’ compensation.
If the responsible payer does not pay promptly, Medicare may make a conditional payment for covered care. That payment may later be subject to recovery when a settlement, judgment, award or other payment occurs.
This is separate from the ordinary question of whether a hospital bill was correctly processed by health insurance.
💰 Medicare Conditional Payments
CMS explains that the Benefits Coordination & Recovery Center identifies conditional payments related to a liability, no-fault or workers’ compensation matter. A Conditional Payment Letter can list claims Medicare has identified as related to the pending case.
The amount in a Conditional Payment Letter is interim because additional related payments can occur while the claim is pending. CMS provides a process for disputing charges believed to be unrelated.
For a more detailed discussion, see How Medical Liens Work in Mesothelioma Claims.
🩺 Employer and Private Health Plans
Employer and private plans can have different networks, authorization requirements, deductibles, coinsurance, formularies and appeal procedures. Obtain the current Summary Plan Description, Summary of Benefits and Coverage or equivalent plan documents and use them when reviewing a disputed claim.
The Department of Labor recommends checking plan documents for where to file, what information to provide and whom to contact. Keep copies of all submissions.
🏥 Work With Hospitals and Treatment Centers
Ask major treatment centers whether they have financial counselors, insurance coordinators or patient advocates. These teams may help identify prior-authorization problems, correct billing information, clarify network status and communicate with insurers.
When a provider says “insurance denied it,” ask for the claim number and denial reason. When an insurer says “the provider must resubmit,” give that information back to the provider’s billing office and document the exchange.
💊 Prescription Drug Claims
Prescription coverage may operate through a separate pharmacy benefit or Medicare drug plan. Keep denial notices involving prior authorization, formulary restrictions, quantity limits or step requirements and ask the prescribing team whether medical documentation is needed for an exception or appeal.
Do not delay medically necessary treatment solely to resolve paperwork without discussing the situation with the treating medical team.
🚗 Travel and Out-of-Pocket Expenses
Keep receipts for deductibles, copayments, coinsurance, prescriptions, medical equipment and treatment-related travel. Some expenses may not be covered by health insurance but can still be important when documenting the financial impact of treatment or a separate compensation claim.
Record the date, purpose, amount and person who paid each expense. A credit-card statement alone may not explain why an expense was medically related.
⚖️ Keep Health Insurance Separate From the Mesothelioma Claim
Families often manage several processes at once. A health-insurance claim seeks payment under a health plan. A workers’ compensation claim, asbestos trust claim or civil lawsuit follows different rules and may involve different evidence and deadlines.
Keep separate folders for medical billing, health-insurance appeals and legal compensation records. Cross-reference documents when necessary, but do not assume that filing one type of claim preserves rights under another.
📁 Records Families Should Preserve
- Insurance cards and plan documents
- Medicare Summary Notices and EOBs
- Provider bills and itemized statements
- Claim numbers and denial notices
- Prior-authorization correspondence
- Appeals and supporting medical documentation
- Proof of submission and delivery
- Prescription claim records
- Coordination-of-benefits correspondence
- Medicare conditional-payment correspondence
- Receipts for copays and other out-of-pocket expenses
- Family call logs and representative authorizations
Families preserving records for a future compensation matter may also find How Families Can Preserve Evidence for Future Claims useful.
🕊️ Insurance Records After a Family Member Dies
Do not immediately discard insurance, Medicare or billing records after a death. Outstanding claims, corrected bills, appeals, refunds or reimbursement questions can continue afterward. Preserve records showing what was billed, paid, denied and still outstanding.
Authority to communicate with an insurer after death may depend on estate documents, plan procedures and applicable law. Keep executor or personal-representative documents available when relevant.
⚠️ Common Insurance-Management Mistakes
- Paying a large bill before comparing it with the EOB or Medicare notice.
- Throwing away denial notices after calling the insurer.
- Missing an appeal deadline while waiting for a provider to resubmit.
- Assuming every family member can automatically discuss protected claim information.
- Failing to update coordination-of-benefits information.
- Keeping only the latest bill and discarding earlier versions.
- Confusing a Medicare conditional-payment amount with a final recovery demand.
- Mixing health-insurance records with legal-claim documents without an index.
✅ Family Insurance Claim Checklist
- List every health plan and policy.
- Identify primary and secondary coverage.
- Complete representative authorizations.
- Create a claim and billing spreadsheet or log.
- Save every EOB and Medicare Summary Notice.
- Match provider bills to insurance decisions.
- Record every denial reason.
- Calendar appeal deadlines immediately.
- Keep complete copies of appeals.
- Save proof that an appeal was received.
- Track prior authorizations.
- Keep prescription and pharmacy records.
- Preserve out-of-pocket receipts.
- Maintain Medicare conditional-payment correspondence separately.
- Keep insurance records after death until outstanding issues are resolved.
❓ Frequently Asked Questions
Can a family member handle insurance claims for someone with mesothelioma?
Often yes, but the insurer may require authorization or appointment as a representative before discussing protected information or accepting an appeal.
Is an Explanation of Benefits a bill?
Not necessarily. An EOB explains how the insurer processed a claim. Compare it with the provider’s bill before determining what is actually owed.
What should we do when a claim is denied?
Read the written denial, identify the reason and deadline, obtain relevant records and follow the plan’s appeal procedure.
How long do we have to appeal a private health-plan denial?
The exact deadline depends on the plan and governing rules. For many ERISA-governed health plans, the Department of Labor states that claimants have at least 180 days to request review of a denied claim. Always follow the specific denial notice and plan documents.
Can Medicare decisions be appealed?
Yes. Medicare provides appeal rights for qualifying coverage and payment decisions, with procedures depending on Original Medicare or the type of Medicare plan.
Can a family member represent someone in a Medicare appeal?
Yes, a beneficiary can appoint a trusted person as a representative using Medicare’s procedures.
What is coordination of benefits?
It is the process used when more than one payer may cover care to determine which payer is responsible first and how another payer may contribute.
What is a Medicare conditional payment?
It is a payment Medicare may make for covered care when another payer may be responsible but does not pay promptly. Medicare may later seek reimbursement after a settlement, judgment, award or other payment.
Is a Medicare Conditional Payment Letter amount final?
No. CMS describes the amount as interim because additional related payments can occur while the case remains pending.
Should we keep medical bills after insurance pays?
Yes. Keep the bill, EOB or Medicare notice and payment information together so the family can document what was charged, allowed, paid and assigned to the patient.
Should insurance records be kept after death?
Yes, at least while unresolved claims, bills, appeals, reimbursements or estate-related matters remain. Authority to act afterward may depend on estate and plan procedures.
Is a health-insurance claim the same as an asbestos compensation claim?
No. Health insurance pays benefits under a health plan, while asbestos lawsuits, trust claims and workers’ compensation use separate legal processes and deadlines.
📞 Request a Case Evaluation
If a family member has been diagnosed with mesothelioma, preserve medical bills, insurance records, Medicare notices, denial letters, appeal records and any correspondence involving reimbursement or other payers. Keep these records separate from—but coordinated with—employment and asbestos-exposure evidence.
Call 800.291.0963 for a no-obligation case evaluation and to talk to a real person 24/7, 365 days a year. Many mesothelioma law firms handle qualifying cases on a contingency-fee basis; confirm the fee agreement and terms directly with the firm you retain. Submit your case here.
📝 Summary
Families can make mesothelioma insurance administration more manageable by centralizing records, identifying all coverage, appointing an authorized representative, matching bills to EOBs, tracking denials and appeals, and keeping Medicare coordination and conditional-payment issues separate from ordinary health-plan claims. Preserve complete records and deadlines rather than relying on phone conversations alone. Health insurance, Medicare recovery and asbestos compensation can interact, but each follows its own rules and should be tracked separately.
🔗 Confirmed Sources
- U.S. Department of Labor — Filing a Claim for Your Health Benefits
- Medicare — Filing an Appeal
- CMS — Coordination of Benefits
- CMS — Conditional Payment Information
- CMS — Medicare’s Recovery Process
Disclaimer: General information only—not legal, medical, financial or insurance advice. This website is not a law firm or insurance company. Coverage, appeals, coordination of benefits, Medicare recovery rights and legal claims depend on the specific plan, facts and governing law. Always follow the deadline and instructions in the applicable plan or government notice.