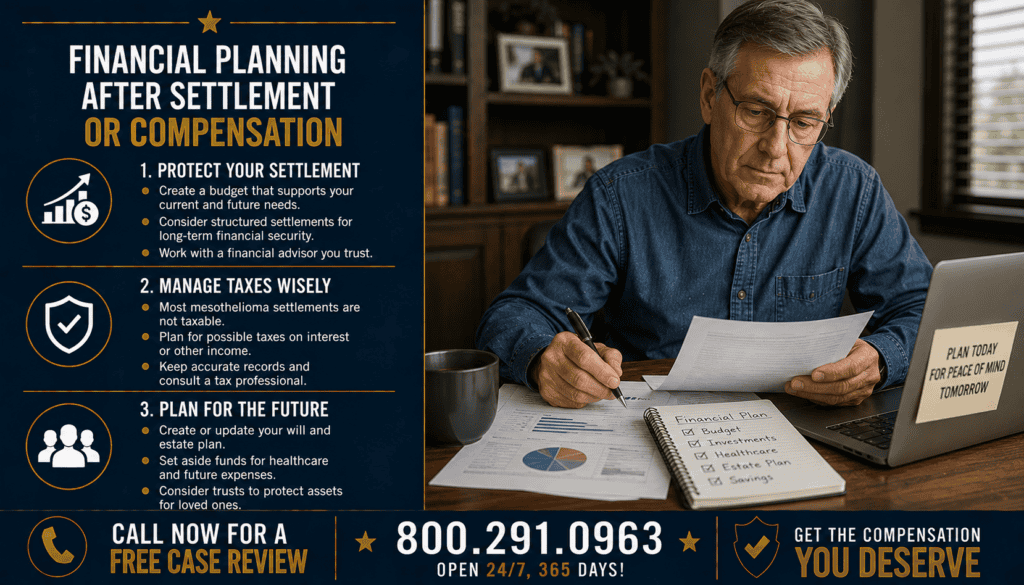
Financial Planning After Settlement Or Compensation
Exposure, Evidence and Claims
A mesothelioma settlement may provide financial support for treatment, household expenses, and family needs. Careful planning starts with understanding the net amount received, outstanding obligations, and how long the money may need to last.
Financial planning after settlement or compensation also involves taxes, public benefits, account safety, and estate documents. The following steps help families organize decisions while identifying questions for qualified legal, tax, and financial professionals.
Understanding Your Settlement Funds
Receiving compensation after a mesothelioma claim can create immediate decisions at a time when treatment, caregiving, and family responsibilities are already demanding. The first step is to distinguish the amount described in a settlement agreement from the money actually available for household planning. Attorney fees, case expenses, medical liens, reimbursements, and other authorized deductions may affect the net distribution. Request a written disbursement statement and keep a copy with the signed agreement. Do not assume that the headline settlement figure is the amount you can spend.
If payments come from several defendants or asbestos bankruptcy trusts, distributions may arrive on different dates and under different paperwork. A practical financial plan should use funds actually received, not anticipated payments. Ask the attorney handling the claim which obligations must be resolved before funds can be released. If the payment belongs to an estate, trust, or multiple claimants, obtain appropriate legal guidance before transferring or distributing it. A clear starting balance protects against accidental overcommitment.
Reviewing Fees, Liens, And Obligations
Before assigning money to long-term goals, review the final settlement accounting line by line. Identify the gross recovery, attorney compensation, reimbursed litigation costs, outstanding medical bills, and any lien amounts that were negotiated or satisfied. Some insurers, government programs, or providers may assert repayment rights depending on the facts and applicable law. Ask for documentation of how each amount was calculated. Do not independently ignore a notice of reimbursement or presume every bill is valid.
If a lien is disputed, request that your attorney explain the resolution process. Keep invoices and payment confirmations together so a later inquiry can be answered without reconstructing the case. Families should also distinguish current household debts from claims-related deductions. Credit cards, mortgages, and personal loans require their own review after the legal distribution is understood. If a relative helped pay expenses during treatment, document whether repayment is a gift, loan, or agreed reimbursement before making transfers.
Careful records make future planning more reliable.
Building A Medical And Care Reserve
Mesothelioma treatment can involve ongoing appointments, prescriptions, travel, supportive services, and periods when family members cannot work their normal schedules. A reserve for foreseeable medical and caregiving expenses can help protect the household from having to liquidate investments at an inconvenient time. Start by listing known insurance premiums, deductibles, copayments, transportation, lodging, mobility equipment, and assistance at home. Separate confirmed expenses from possible future costs; no single projection fits every diagnosis or treatment plan. Ask the care team and insurance administrator about expected coverage and preauthorization requirements.
Keep enough readily accessible cash for expenses that could arise before insurance reimbursement or another compensation payment. Where a patient relies on public benefits, discuss the effect of receiving and holding funds with a qualified benefits adviser before changing account ownership. Financial planning should support medical choices rather than substitute for advice from the treating clinicians.
Creating A Household Spending Plan
A settlement may need to support a household through reduced income, increased expenses, or a surviving spouse’s future needs. Begin with a monthly spending worksheet that includes housing, utilities, food, insurance, transportation, debt payments, and dependable income from employment or benefits. Next, estimate expenses that occur only occasionally, such as property taxes, major repairs, and vehicle replacement. Put near-term needs in a separate category from long-term savings. If a patient has stopped working, examine whether the budget remains sustainable after wages cease or disability benefits change.
Avoid using an assumed investment return to close an immediate cash shortfall. Review the plan together with anyone who shares responsibility for household finances, while respecting the recipient’s legal control over the proceeds. A conservative initial budget gives the family time to understand its new financial position. Revisit the numbers after medical bills, insurance claims, and other obligations become clearer.
Understanding Tax Treatment
The tax treatment of lawsuit proceeds depends on what each payment compensates. Under federal rules, compensatory damages received because of personal physical injury or physical sickness are generally excluded from gross income, but important exceptions exist. Punitive damages and interest may be taxable, and recovery of previously deducted medical expenses can create tax consequences to the extent the earlier deduction produced a tax benefit. The treatment of attorney fees can also depend on the underlying recovery. Asbestos trust payments, wrongful-death proceeds, and settlements involving several types of damages require examination of their actual documents and applicable state and federal law.
Do not describe every mesothelioma settlement as automatically tax-free. Retain the settlement agreement, allocation schedules, disbursement records, and any tax forms received. Ask a certified public accountant or qualified tax professional to review the transaction before filing. The Internal Revenue Service publishes guidance on settlements and judgments, including Publication 4345. Tax advice should be tailored to the actual award rather than a generic online example.
Protecting Public Benefits And Eligibility
A settlement can interact with public benefits in ways that are easy to overlook. Some programs consider income, some consider assets, and some use different eligibility rules altogether. For example, needs-based programs may require careful review before a large payment is deposited or transferred. Medicare, Medicaid, Supplemental Security Income, veterans benefits, and private disability policies are not interchangeable programs. Eligibility and reporting requirements can differ substantially.
A recipient should not move funds to another person or establish a trust based only on a suggestion found online. Certain trusts or planning arrangements may be appropriate in specific circumstances, but they require knowledgeable legal review and may carry administrative costs. Before taking action, gather award documents and a current list of benefits, then consult an attorney or benefits specialist familiar with the relevant programs and state rules. A small amount of advance planning can prevent expensive misunderstandings or avoidable interruptions in assistance.
Choosing Safe Accounts And Professional Help
For money needed soon, prioritize accessibility and protection of principal over speculative returns. Confirm that any bank or credit union is appropriately insured and understand the applicable deposit-insurance limits, including how account ownership affects coverage. Do not leave large balances in an unfamiliar account simply because a salesperson recommends it. If the family needs investment advice, interview a credentialed professional and ask whether they act as a fiduciary, how they are compensated, and whether they receive commissions or referral fees. Request a written explanation of fees, investment risk, withdrawal restrictions, and conflicts of interest.
Avoid promises of guaranteed high returns, urgent deadlines, or secret investment opportunities. Be cautious about unsolicited calls after a settlement becomes public. A second opinion can be especially valuable before purchasing annuities, illiquid investments, or complex insurance products. The best arrangement depends on the time horizon, household obligations, and ability to tolerate loss.
Planning For Family And Estate Needs
Financial planning after a settlement often includes decisions about a spouse, children, dependents, and the management of assets if health circumstances change. Review existing wills, powers of attorney, health-care directives, and beneficiary designations with qualified professionals. A beneficiary named on an account may receive funds outside the instructions in a will, so inconsistent paperwork can create disputes. If compensation belongs to an estate or wrongful-death beneficiaries, do not assume one family member can distribute it informally. State law and the settlement documents may control who receives the proceeds.
Families with minor children or dependents who receive needs-based benefits may need additional planning. Keep an organized folder of legal contacts, insurance policies, account locations, and important instructions, stored securely. Discuss responsibilities in advance where possible, but avoid publishing account numbers or sensitive documents in shared messages. Thoughtful preparation can reduce administrative stress for loved ones.
Avoiding Financial Mistakes And Scams
The period immediately after receiving compensation can attract sales pressure and requests for money. Avoid making large gifts, loans, purchases, or investments before the family has reviewed its budget and obligations. Fraudsters may impersonate attorneys, banks, government agencies, or financial advisers and ask for wire transfers or account credentials. Verify payment instructions by calling a trusted number already on file, not a number supplied in an unexpected message. If compensation is paid over time, be particularly cautious about companies offering immediate cash in exchange for future payments.
The Consumer Financial Protection Bureau warns that selling structured-settlement payments can produce substantially less cash than the payments are worth. Ask for a written comparison of total remaining payments, the proposed lump sum, and every fee or discount. Independent legal and financial advice is important before signing. Slow decisions are often safer than irreversible decisions made under pressure.
Related Mesothelioma Lawsuit Resources
Explore related site sections for additional context:
- Mesothelioma Lawsuit
- Mesothelioma Settlements & Compensation
- Veterans Asbestos Exposure
- Asbestos Companies
- Job Sites Asbestos Exposure
- High-Risk Jobs
❓ Frequently Asked Questions
Is Mesothelioma Settlement Compensation Taxable?
Compensation for physical sickness is generally excluded from federal income tax, but punitive damages, interest, and some previously deducted medical expenses can be exceptions. Review the actual allocation with a tax professional.
Should I Pay Off Debt Immediately?
First identify medical obligations, household cash needs, interest rates, and emergency reserves. Paying expensive debt can help, but draining accessible funds may create a new problem.
Can A Settlement Affect Medicaid Or SSI?
It can, depending on the program, timing, assets, and applicable rules. Obtain benefits-specific legal advice before moving money or changing ownership.
Do I Need A Financial Adviser?
Not every family needs ongoing investment management. A fee-transparent fiduciary or qualified planner can help with budgeting, taxes, risk, and long-term decisions.
How Much Should Be Kept For Medical Expenses?
There is no universal amount. Estimate likely uncovered costs with the care team and insurer, then maintain accessible reserves suited to the household.
Are Structured Settlement Buyouts Safe?
They may involve substantial discounts and fees. Compare the full value of future payments with the cash offered and seek independent advice.
What Documents Should I Keep?
Retain settlement agreements, disbursement statements, lien resolutions, tax forms, medical receipts, benefit notices, and financial-account records.
Can Settlement Money Be Left To Family Members?
Often estate and beneficiary planning can address future transfers, but the answer depends on ownership, settlement terms, and state law. Consult an estate attorney.
Reliable Public Resources
Review IRS settlement tax guidance, IRS Publication 4345, and CFPB structured settlement warnings.
📞 Get the Mesothelioma Help & Compensation You Deserve — Contact Us Today!
CALL 800.291.0963 | LIVE CHAT 24/7/365 | CONTACT FORM
Disclaimer: This information is not be considered as legal or medical advice. Mesothelioma Help Center is not a law firm or medical provider and does not determine legal or VA eligibility.